Germany brings in new rules on access to debt counselling from 20 November 2026 – in the UK, free, independent debt advice already runs through MoneyHelper, StepChange, National Debtline and Citizens Advice, while the FCA tightly regulates fee-charging firms.
Key points
- From 20 November 2026, Germany’s new Schuldnerberatungsdienstegesetz (Debt Counselling Services Act) sets legal rules for access to independent debt counselling there.
- In the UK, free and impartial debt advice is funded through the government-backed Money and Pensions Service via MoneyHelper, alongside charities StepChange, National Debtline and Citizens Advice.
- The Financial Conduct Authority (FCA) regulates fee-charging debt management firms: under its CONC 8 rules, they must disclose any fee and how it is worked out before a customer signs up, and must point customers towards free advice.
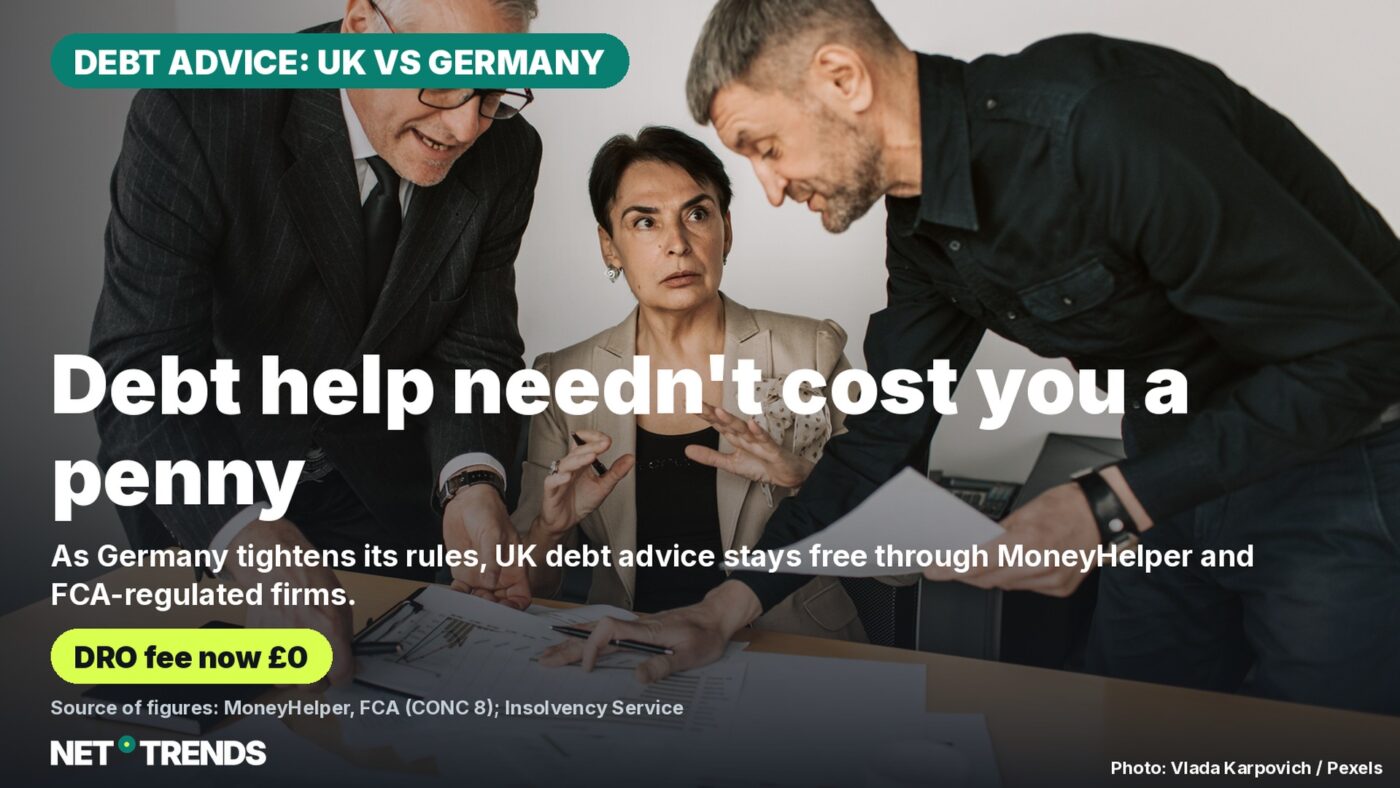
- Since 6 April 2024, applying for a Debt Relief Order – a free, formal route out of debts up to £50,000 – no longer carries the previous £90 administration fee.
Germany is introducing a new federal law on access to debt counselling from 20 November 2026 – a reminder that free, independent help with debt problems is also available to people in the UK, without needing to go through a fee-charging firm first. UK consumers struggling with repayments can reach government-backed and charity debt advice at no cost, while firms that do charge are bound by Financial Conduct Authority rules on fee transparency.
In Germany, the Schuldnerberatungsdienstegesetz (SchuBerDG) – which implements the EU’s Consumer Credit Directive 2023/2225 – takes effect for most of its provisions on 20 November 2026. It sets out who counts as independent debt counselling under German law and requires providers there to disclose in advance if, and how much, they charge; it does not set a single nationwide fee and does not guarantee free advice in every case. The UK, outside the EU since Brexit, is not bound by that directive or by German law, and has its own separate system for regulating debt advice and debt solutions – summarised below.
Where to get free debt advice in the UK
The main government-backed channel is MoneyHelper, run by the Money and Pensions Service (MaPS) – an arm’s-length body sponsored by the Department for Work and Pensions and funded by levies on the financial services industry and pension schemes, according to MaPS’ own description of itself. MaPS describes itself as the biggest funder of free debt advice in England, delivered through a network of partner organisations rather than directly.
Alongside MoneyHelper, the best-known free, not-for-profit debt advice charities in the UK are StepChange, National Debtline (run by the Money Advice Trust) and Citizens Advice, which offer confidential advice on managing debt, checking entitlement to benefits, and explaining the available options, including formal insolvency routes.
How the FCA regulates fee-charging debt firms
Not every provider is free. The Financial Conduct Authority (FCA) regulates commercial debt management firms and so-called debt packagers – firms that assess a person’s situation and often refer them on to a debt solution provider. Under the FCA’s Consumer Credit sourcebook, CONC 8, a debt management plan provider must tell a customer the fee amount before they agree to a plan or, if that is not yet possible, explain exactly how the fee will be calculated, and must explain how any fee affects how long the plan runs and the total a customer ultimately pays.
The rules also require firms to tell customers how to access free debt advice before they sign up, and to refer them to not-for-profit advice organisations for further help where appropriate; if a debt management plan is not in a customer’s best interest, the provider must offer suitable alternatives, including withdrawing.
“Debt management is one of the UK’s highest risk consumer credit sectors.”
Financial Conduct Authority, publishing its review of debt management firms
The FCA has acted on this before: in June 2023 it banned debt packager firms from taking referral fees from the debt solution providers they recommend customers to, after finding the fee model gave some firms an incentive to push people towards costlier options – such as an Individual Voluntary Arrangement (IVA) or, in Scotland, a Protected Trust Deed, which the FCA said can cost a consumer £3,650 or more over its lifetime – rather than cheaper statutory routes that earn the firm nothing.
Debt Relief Orders: the fee has gone
For people with relatively low debts and no significant assets, a Debt Relief Order (DRO) is a formal, free route to writing off qualifying debts. Since 6 April 2024, the Insolvency Service has scrapped the £90 administration fee that previously applied, meaning a DRO application itself no longer costs anything. From 28 June 2024, the eligibility thresholds were also widened: the total qualifying debt limit rose from £30,000 to £50,000, and the limit on the value of a vehicle someone can keep rose from £2,000 to £4,000.
A DRO still has to be applied for through an authorised debt adviser rather than directly by the individual, and it is not automatically the right option for everyone – an adviser at a free service such as StepChange, National Debtline, Citizens Advice or via MoneyHelper’s debt advice locator can help work out whether it, a different statutory route, or a debt management plan fits a particular situation.
What to check before you get advice
Checklist before contacting a debt advice provider
- Check whether the service is free: MoneyHelper’s debt advice locator, StepChange, National Debtline and Citizens Advice do not charge for advice.
- If a firm does charge, ask for the exact fee, or how it is calculated, before agreeing to anything – this is a legal requirement under the FCA’s CONC 8 rules.
- Ask whether the firm is authorised by the FCA; a legitimate fee-charging provider must still point you towards free advice.
- Before paying into any commercial debt solution, ask an adviser whether a free statutory route – such as a Debt Relief Order – might apply instead.
These steps don’t replace a full conversation with a debt adviser, but they help anyone contacting a provider for the first time avoid an unexpected bill.
Frequently asked questions
Is debt advice in the UK always free?
No, but the main government-backed and charity routes are: MoneyHelper’s debt advice locator, StepChange, National Debtline and Citizens Advice do not charge. Commercial debt management firms can charge a fee, but under FCA rules they must disclose it upfront and point customers towards free alternatives.
What does the FCA require fee-charging debt firms to do?
Under CONC 8, a debt management plan provider must tell a customer the fee amount, or how it will be worked out, before they agree to a plan, explain how fees affect the plan’s length and total cost, and signpost free debt advice. In June 2023, the FCA also banned referral fees for debt packager firms.
Does a Debt Relief Order still cost £90?
No. The Insolvency Service removed the £90 administration fee from 6 April 2024, so applying for a Debt Relief Order no longer carries that charge. From 28 June 2024, the qualifying debt limit also rose from £30,000 to £50,000.
Does Germany’s new debt counselling law affect people in the UK?
Not directly. The Schuldnerberatungsdienstegesetz is German federal law implementing an EU directive; since Brexit the UK is not bound by EU consumer credit rules and regulates debt advice separately through the FCA and the Money and Pensions Service.
Sources and status
- MoneyHelper: Debt advice locator, moneyhelper.org.uk, accessed 8 November 2026.
- Money and Pensions Service: “Who we are”, maps.org.uk, accessed 8 November 2026.
- Financial Conduct Authority: FCA Handbook, CONC 8.2, handbook.fca.org.uk, accessed 8 November 2026.
- Financial Conduct Authority: “Debt management firms still failing Britain’s most vulnerable consumers, says FCA”, fca.org.uk, 25 June 2015.
- Report on the FCA’s 2023 referral-fee ban for debt packager firms: MoneyAge, “FCA to ban referral fees for debt packagers”, 2 June 2023.
- UK Insolvency Service / GOV.UK: “Changes to Debt Relief Orders will support people in financial distress”, gov.uk, accessed 8 November 2026.
- For background on the German law: Schuldnerberatungsdienstegesetz (SchuBerDG), gesetze-im-internet.de (in German).
Research and legal status as of: 8 November 2026. UK figures and rules are liable to change; always check current fees and eligibility directly with the provider or the Insolvency Service.
Transparency note: AI-assisted tools were used in researching, structuring and writing this article. The sources used are listed in the article. Publication takes place only after manual editorial approval. Country edition based on an article from Net Trends, researched for the UK.
Share this article